
Bank Valuation of Property: Fixable Factors Lowering Value
Introduction
Waiting on a property valuation can be stressful, especially if the final figure comes in much lower than anticipated. Many property owners lose valuable equity due to simple, easily rectifiable presentation and maintenance issues. By identifying and resolving minor red flags before an inspector arrives, you can better prepare for an independent property valuation and ensure your property’s condition is accurately assessed.
Summary
This guide breaks down how property valuations work, explaining key differences between bank valuations and real estate market appraisals. It highlights ten fixable factors that actively reduce valuation figures—including poor kerb appeal, deferred repairs, water damage, unpermitted structures, and interior clutter. Additionally, it clarifies unfixable market conditions and provides a practical pre-inspection checklist to help you present your home in the best light.
Bank Valuation of Property: Factors That Decrease Value
What a Bank Valuation Is and Why It Matters
A bank valuation is an independent risk assessment ordered by a lender to determine how much money they can safely lend against a property. Unlike an agent’s market appraisal, understanding the difference between a bank valuation vs independent property valuation can help property owners understand how each assessment serves a different purpose.
An assessment directly impacts your financial positioning in three main ways:
- Loan-to-Value Ratio (LVR): A lower valuation increases your LVR, which can trigger extra expenses like Lenders Mortgage Insurance (LMI).
- Borrowing Capacity: It establishes the hard limit on how much equity you can release for refinancing or reinvesting.
- Loan Approvals: If a valuation comes in under a purchase contract price, buyers must supply a larger cash deposit to bridge the gap.
Common Fixable Factors That Lower Property Value
Minor neglect quickly accumulates and signals deferred maintenance to an inspector. Resolving these ten practical items before your appointment helps safeguard your valuation:
- Poor Kerb Appeal: Overgrown lawns, dirty driveways, and unkempt gardens create a poor initial impression. Mow, weed, and pressure-wash outdoor walkways.
- Deferred Maintenance: Broken tiles, peeling paint, cracked fencing, and leaky gutters lead valuers to deduct estimated repair costs directly from your final figure.
- Damp and Mould: Water stains and bathroom mould hint at underlying plumbing or structural issues. Fix leaks at the source, improve ventilation, and repaint.
- Unpermitted Improvements: Unapproved decks, pergolas, or granny flats are often discounted or completely excluded from valuations. Seek retrospective council certification where possible.
- Outdated Fixtures: Dated kitchens and bathrooms reduce perceived overall condition. Modernize these spaces affordably by re-grouting tiles, changing tapware, and swapping cabinet hardware.
- Clutter and Lack of Access: Messy rooms make spaces feel smaller and prevent valuers from fully inspecting the home’s condition.
- Safety Non-Compliance: Non-functional smoke alarms, unsafe wiring, or non-compliant pool fencing create major red flags.
- Poor Natural Lighting: Dark interiors feel smaller. Trim back overgrown trees blocking windows and swap out heavy drapes for sheer curtains.
- Unmanaged Pests: Evidence of active or past termite damage spooks lenders. Keep up-to-date pest control documentation on hand.
- Neglected Outdoor Spaces: Unmaintained yards or green pools signal ongoing maintenance burdens. Clean and balance pool water before the inspection.
During a bank valuation of property, physical presentation and apparent maintenance levels directly influence the final report.
Unfixable Factors to Keep in Mind
While physical presentation is fully within your control, certain structural and market factors cannot be altered:
- Location specifics, such as proximity to flight paths, flood zones, or busy roads, can influence marketability and value depending on the severity of the exposure and local buyer demand.
- Local council zoning limits and total block size
- Broader economic factors, including interest rates and recent neighborhood sales trends
Pre-Inspection Preparation Checklist
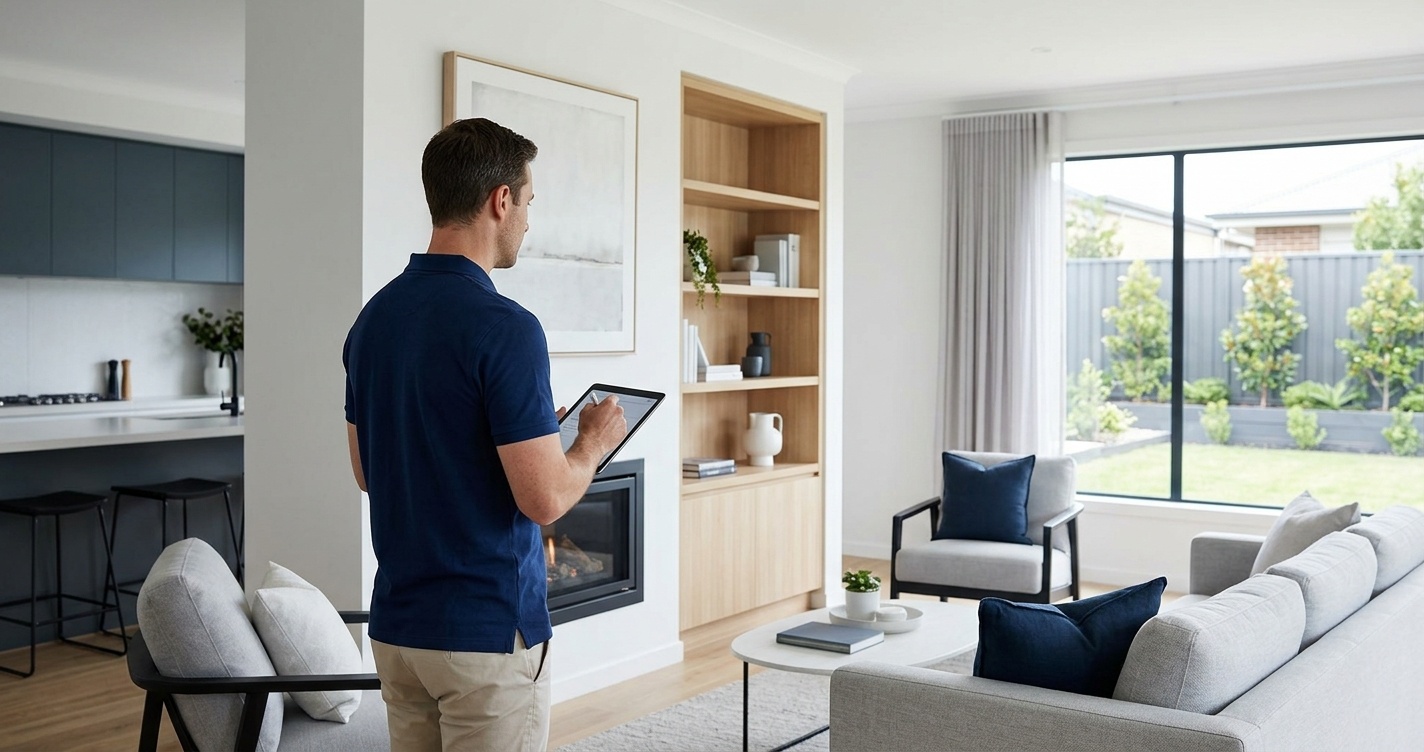
To ensure your bank valuation of property reflects its true market potential, complete these steps prior to the valuer’s arrival:
- Clean and declutter living areas, garages, sheds, and yards.
- Ensure clear physical access to all rooms, roof spaces, and subfloor areas.
- Organize paperwork for building approvals, council permits, and pest warranties.
- Prepare a concise, written list detailing recent capital upgrades and renovation costs.
Frequently Asked Questions
Can I be present during the property valuation?
Yes. Property owners are generally welcome to attend physical inspections to provide access, answer questions, and highlight recent structural improvements.
Why do bank valuations come in lower than market appraisals?
Bank assessments focus on lender risk and quick-liquidation value, whereas agent market appraisals reflect optimistic selling scenarios in open market conditions.
How long is a bank valuation valid?
Most lender valuations remain valid for 60 to 90 days. If market conditions shift rapidly, a lender may require an updated assessment sooner.
Does renovating guarantee a higher valuation?
Not always dollar-for-dollar. Valuers assess renovations based on build quality, council compliance, and local market expectations rather than the total amount spent.
Conclusion
Achieving an accurate property valuation largely comes down to maintenance, presentation, and proper documentation. Addressing minor defects, rectifying unapproved structures, and cleaning key living areas ensure your property presents in optimal condition. Taking these simple steps before an inspector arrives protects your hard-earned equity and keeps your broader financial goals on track.
Need an accurate, independent property valuation? Contact the accredited team at Budget Property Valuations today on +61 438 080 786 to discuss your valuation needs.